The 3rd of the month arrives. You meant to move something into savings when you got paid, but “when there’s some left” came and went.
Tonight you remember a bill that’s due tomorrow, and you’re not quite sure the rent has left yet. None of this is a crisis. It’s just a dozen tiny chores, humming in the back of your mind.
Sound familiar? Here’s the thing: you’re not bad with money. You’re doing too many money jobs by hand, and every one of them needs a reminder, a decision, and a little bit of luck.
Today’s habit is one quiet hour, once. You set a few automations — a transfer to savings after payday, automatic payment for the bills that never change, a separate pot for the costs that show up once a year — and then you let them run. No new app, no new personality, no willpower required.
The Stress Is in the Chores
Most money stress isn’t one big disaster. It’s the drip of small tasks you have to remember: move the savings, pay the rent, not miss the insurance, check whether that bill already went out. Each one is easy. Together they take up a surprising amount of mental space, even on days you don’t actually open the banking app.
Late fees, missed transfers, and “I’ll do it tomorrow” are usually a memory problem, not a character problem. A system that runs without you is kinder than a system that needs you to be on top of it every week.
If you’ve already done The Subscription Sweep, even better. There’s no point automating a charge you were about to cancel. Sweep first, then put the keepers on a track.
One Hour, Then Let It Run
The idea is almost embarrassingly simple. Sit down once, with a coffee and a list, and tell your bank what to do on your behalf. Your bank may call these tools a standing order, a direct debit, an automatic transfer, or something else. The name doesn’t matter. The “set it and let it run” part does.
This is also how The Weekly Money Date gets easier. In that post, the third week of the challenge was “automate one transfer,” so the date could become a check, not a chore. This is that idea, finished. The automations do the boring work. The Money Date is where you look, catch anything odd, and choose one intentional spend — calmly, with coffee.
Behavioral researchers, including Richard Thaler and Shlomo Benartzi, have shown that people tend to follow through on saving when it’s set up to run automatically, rather than decided from scratch each payday. You don’t need a perfect plan. You need a default that quietly does the right boring thing.
(This isn’t personalized financial advice, and banks work a little differently from place to place. Read the timings on your own account, start smaller than you think, and adjust.)
What to Automate, and What to Keep in Your Hands
Automate the things that are predictable and easy to regret forgetting. Keep the things that need a human look.
- A transfer to savings: timed for after payday, even if the amount is small.
- Fixed bills: rent, utilities, insurance, a phone plan you actually use — the ones that are the same, or almost the same, every month.
- A monthly slice for annual costs: insurance, a holiday, a membership that renews once a year. December shouldn’t have to be a surprise.
And keep these in your hands:
- The week’s variable spending: groceries, meals out, gifts, anything that changes.
- New subscriptions and one-off purchases: your 24-hour pause from the stress spending post still belongs here.
- Anything you’re unsure will have enough in the account.
- The weekly look itself: that’s the Money Date.
If you’ve been practicing One-In, One-Out, you already know the value of a small rule that runs without a big weekend project. Money works the same way. The rule does the work. You just check it.
Start Small, So Nothing Bounces
The fear that stops most of us is a bounced payment: the savings transfer goes out, the rent follows, and the account dips too low. So we do nothing, and the chores stay in our head.
Start smaller than the “proper” amount.
- Begin with a modest savings transfer. €10 or €20 is enough to start. You can raise it later.
- Time it a day or two after payday, not the same morning, in case the pay arrives a little late.
- Leave a buffer in your main account, a cushion so a slightly early bill doesn’t bounce.
- Add bills one at a time, and watch the first cycle actually land.
The first month is a test, not a performance. If something feels tight, lower the savings amount or shift a date. That’s a successful setup, not a failure.
Pay Yourself First
Here’s the order I like, because it makes the good thing happen before the leftover feeling arrives.
- Income lands in your main account.
- A slice goes to savings automatically. You pay yourself first, even if the slice is small.
- Fixed bills are paid automatically from what’s left.
- A monthly slice moves into the annual-cost pot, so the once-a-year bills are already waiting.
- Whatever remains is the week’s money — groceries, fun, the rest of life.
You don’t need five new accounts. One main account, one savings place, and one pot for the yearly stuff is plenty. Some banks let you nickname pots; some just let you open a second savings space. Use whatever you already have.
What This Has to Do With Wellth
An hour now buys you back a dozen little decisions later. That’s the trade.
Health. Fewer 11 p.m. “did the rent go out?” loops means a quieter mind at bedtime. The chores stop tapping you on the shoulder.
Habits. A default compounds. Each payday, the transfer happens whether you felt motivated or not. We talked about taking emotion out of money in the stress spending post; this is the practical setup that lets that idea run.
Smart Money Moves. You miss fewer due dates, you pay yourself first, and you stop using willpower for things a calendar can do. The money you don’t lose to late fees is a quiet little win. The real return is attention you can spend on the rest of your life.
Your 7-Day Autopilot Challenge
Ready, Wellthers? One small step a day. No need to finish everything in an evening.
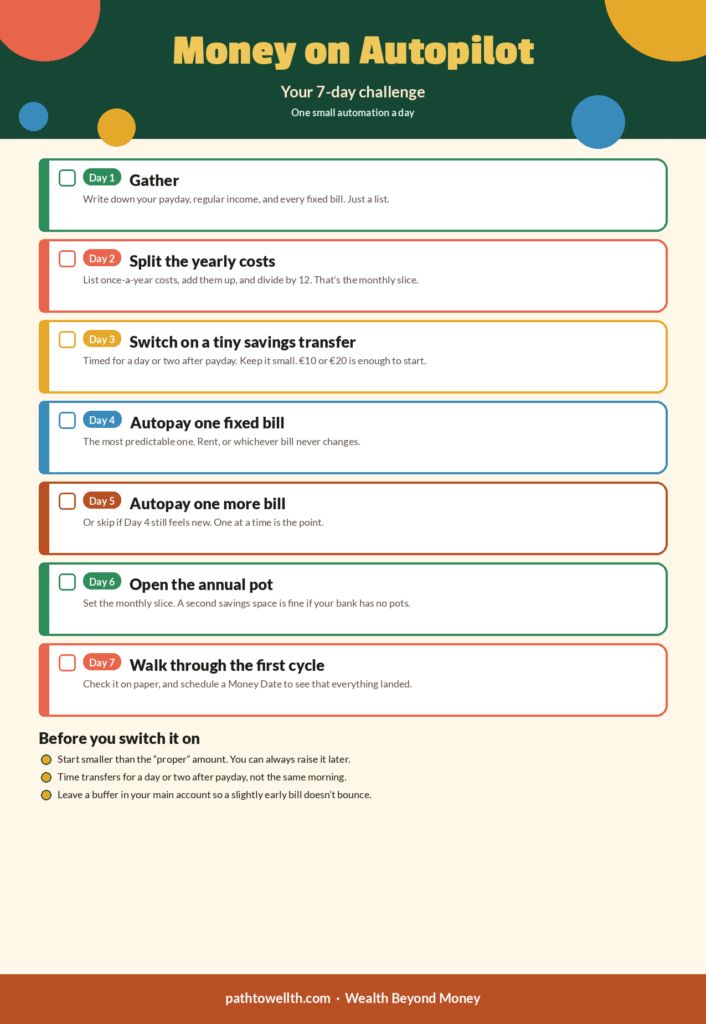
Day 1, Gather: Write down your payday, your regular income, and every fixed bill. Just a list.
Day 2, Split the yearly costs: List the costs that show up once a year, add them up, and divide by 12. That’s the monthly slice for the pot. No setup yet.
Day 3, Switch on a tiny savings transfer: Timed for a day or two after payday. Keep it small.
Day 4, Autopay one fixed bill: The most predictable one. Rent, or whichever bill never changes.
Day 5, Autopay one more bill, or skip if Day 4 still feels new. One at a time is the point.
Day 6, Open the annual pot and set the monthly slice. If your bank doesn’t do pots, a second savings space is fine.
Day 7, Walk through the first cycle on paper, and schedule a Money Date to check that everything landed. Then let it run.
Your Autopilot Checklist
Save it, print it, or stick it near wherever you do your Money Date.
Set It Once, Then Go Live
You don’t need a new budgeting app, a perfect spreadsheet, or a personality transplant. You need one hour, a few automatic moves, and a small buffer so they can run in peace.
Some months you’ll change an amount. Some months a bill will shift and you’ll adjust the date. Both are fine. It’s not about perfection, it’s about taking the boring work off your weekly to-do list so your money — and your mind — can go on autopilot. Your future self will thank you.
So this week, pick a quiet hour, open your banking app, and ask yourself: what would the month feel like if the chores ran themselves, and you only had to look?